
Persistent Systems is growing sales while absorbing the cost of its planned Nagarro acquisition. Its latest results show why those two parts of the business need to be read together.
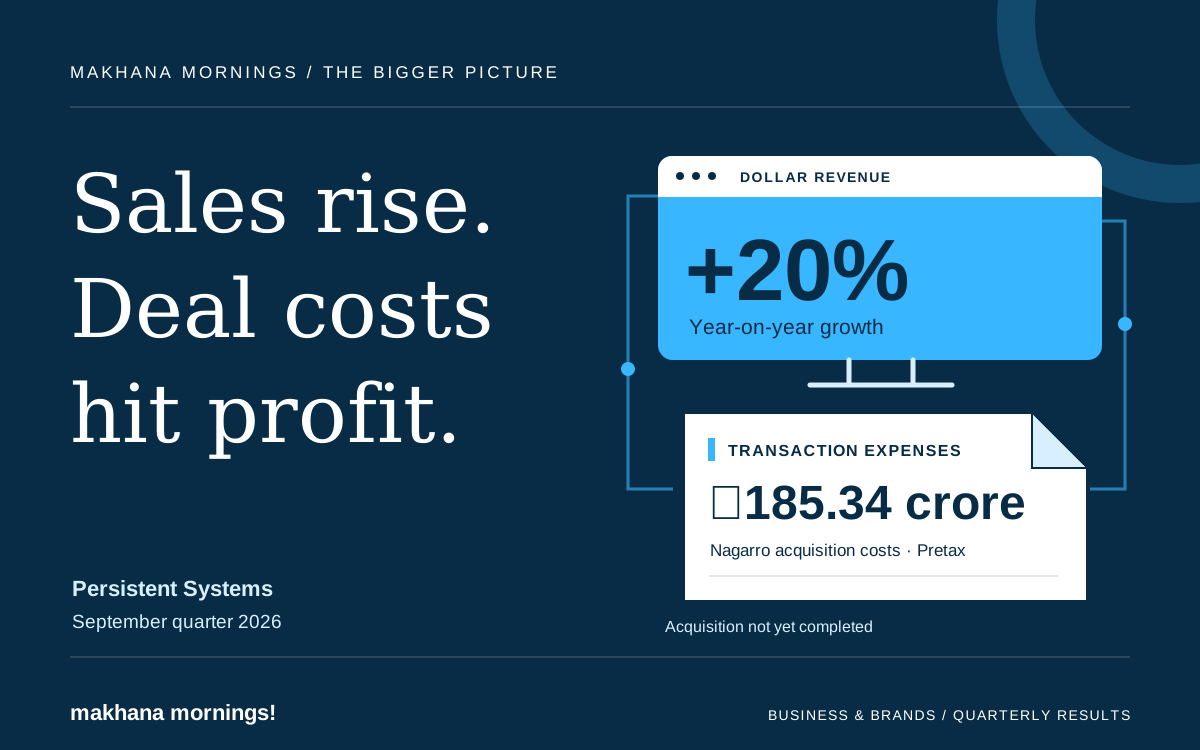
The technology-services company reported revenue of $487.6 million for the quarter ended September 30, 2026, up 20% from a year earlier. Net profit fell 25.4% to ₹351.51 crore, after expenses linked to the proposed deal.
The October 15 results do not signal that Nagarro has joined the group. They show that an acquisition can affect earnings well before it starts contributing revenue.
The Breakdown
Persistent’s dollar revenue rose 7.8% from the previous quarter. In rupees, quarterly sales reached ₹4,663.90 crore, up 30.3% year-on-year.
The dollar and rupee figures express the same revenue in different currencies. Exchange-rate movements boosted rupee-denominated growth. On the company’s constant-currency basis, revenue grew 20.8% year-on-year.
The profit comparison needs a separate adjustment. Persistent incurred ₹185.34 crore of Nagarro-related expenses, including professional fees, legal and regulatory advice, due diligence and valuation work. Its audited accounts include these costs within other expenses.
The company also presents an adjusted measure called operating profit after tax, which excludes the after-tax impact of the deal expenses. That rose 5% to ₹495.15 crore. Reported profit, which includes them, was ₹351.51 crore, against ₹471.47 crore a year earlier.
The adjusted figure helps explain the business’s performance without those transaction costs. It does not make the expenses disappear or replace the reported result.
Why This Matters
There was pressure beyond the acquisition bill. The company’s EBIT margin fell to 15% from 16.3% a year earlier. This measure of profit before interest and tax also excludes the Nagarro deal expenses in Persistent’s presentation.
That means revenue growth did not translate into equally strong profit growth, even before the transaction charge. The headline decline in net profit is only one part of the quarter’s earnings picture.
The Big Picture
On October 9, Persistent said its takeover offer and a separate share-purchase agreement had secured approximately 94.04% of Nagarro’s share capital and voting rights, excluding treasury shares.
That is progress towards an acquisition, rather than confirmation of completion. Persistent expects the transaction to close by the end of March 2027, subject to remaining regulatory approvals. Its October 15 results statement continued to describe work towards closing.
The distinction matters: the latest sales and profit figures should not be read as the performance of an already combined Persistent–Nagarro business.
The Crunch
Persistent has strong sales growth and a large acquisition in progress. Its next challenge is to carry that growth into stronger margins while completing the deal. Separating reported earnings, adjusted earnings and the acquisition timetable makes that challenge easier to see.