
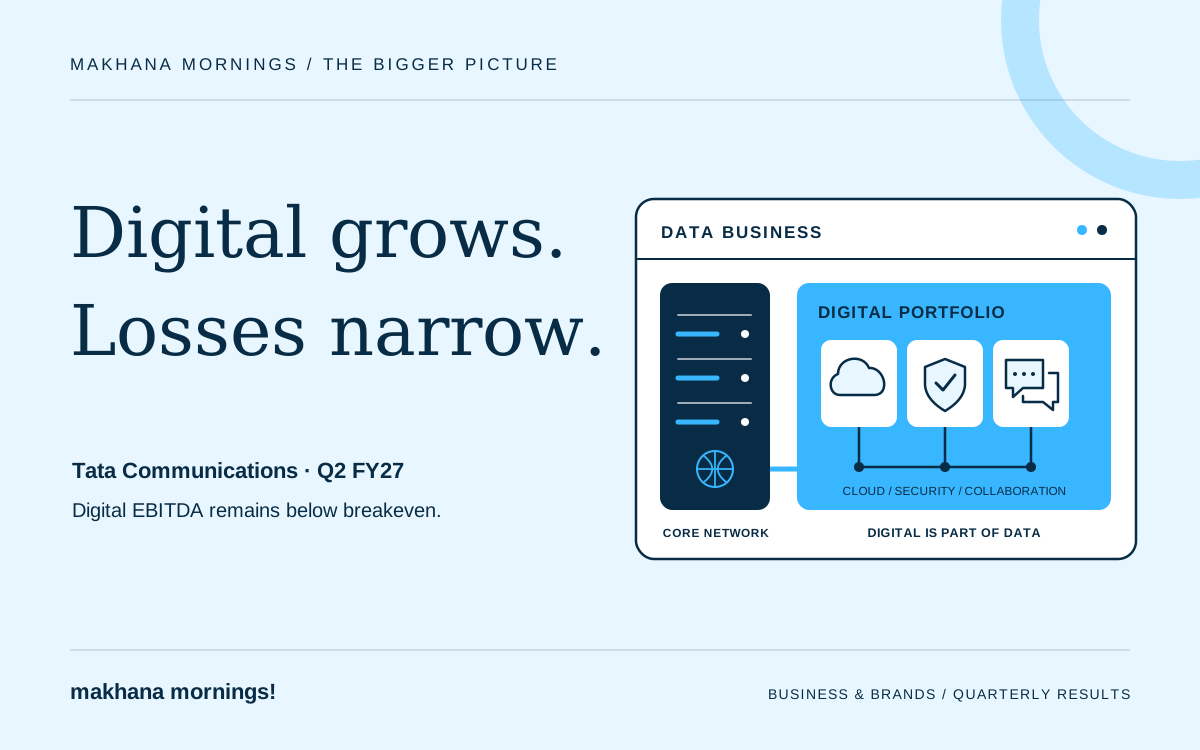
Tata Communications’ digital portfolio is taking up more of its data revenue, while its operating loss is narrowing. Its September-quarter results show progress on both fronts, although the portfolio has yet to reach breakeven.
Digital-portfolio revenue rose 18.6% from a year earlier to ₹3,016 crore in the quarter ended September 30, 2026. The company reported a digital EBITDA loss of ₹107 crore, with the margin improving to minus 3.6% from minus 6.9% in the June quarter.
Those figures, released on October 15, describe a business that is growing while reducing its drag on group earnings. They also leave an important question for the coming quarters: can Tata Communications sustain that improvement as it spends on the infrastructure supporting its next phase of growth?
The Breakdown
Group revenue rose 9.6% year-on-year to ₹6,688 crore. EBITDA, a measure of earnings before interest, tax, depreciation and amortisation, increased 21.2% to ₹1,422 crore. The group EBITDA margin reached 21.3%, against 19.2% a year earlier.
The digital portfolio sits inside the wider data business, alongside core connectivity. It includes collaboration services, cloud and security, newer connectivity products, media, and mobility and internet-of-things services. It now accounts for about 52% of data revenue, according to the company’s investor data pack.
These are overlapping categories. Digital growth and data growth describe different levels of the same business, so their revenues cannot be added together.
Why This Matters
Smaller digital losses help group profitability, but the measure matters. A negative EBITDA margin means the portfolio is still losing money before interest, tax, depreciation and amortisation. Reaching zero on that measure would not, by itself, establish a net profit.
Currency movements also strengthen the headline growth numbers. The company reported data-revenue growth of 12.2%, but its finance chief said growth was about 6% after normalising for currency changes. Digital growth remained in double digits at constant currency, without a precise percentage being given in the prepared commentary.
That distinction helps separate business expansion from the effect of translating overseas revenue into rupees.
The Big Picture
Net profit attributable to the parent’s shareholders rose to about ₹341 crore from ₹183 crore a year earlier, an increase of roughly 86%. This is the company’s profit figure after minority interests.
The group’s profit improvement had more than one source. Other income also improved from a ₹17.24 crore loss to ₹16.41 crore of income, helping reported earnings. Exceptional items moved in the opposite direction: net charges were ₹36.54 crore, compared with ₹21 crore in the September 2025 quarter.
Investment remains substantial. The company reported ₹810 crore of cash capital expenditure and ₹212 crore of free cash flow for the quarter. Net debt stood at ₹11,197 crore. Management said spending was supporting undersea cables and links between data centres.
The Crunch
The next useful milestone is digital EBITDA breakeven, followed by evidence that the improvement can hold as investment continues. The quarter shows progress towards that point. Revenue growth, margins and cash generation together will show how durable it is.