

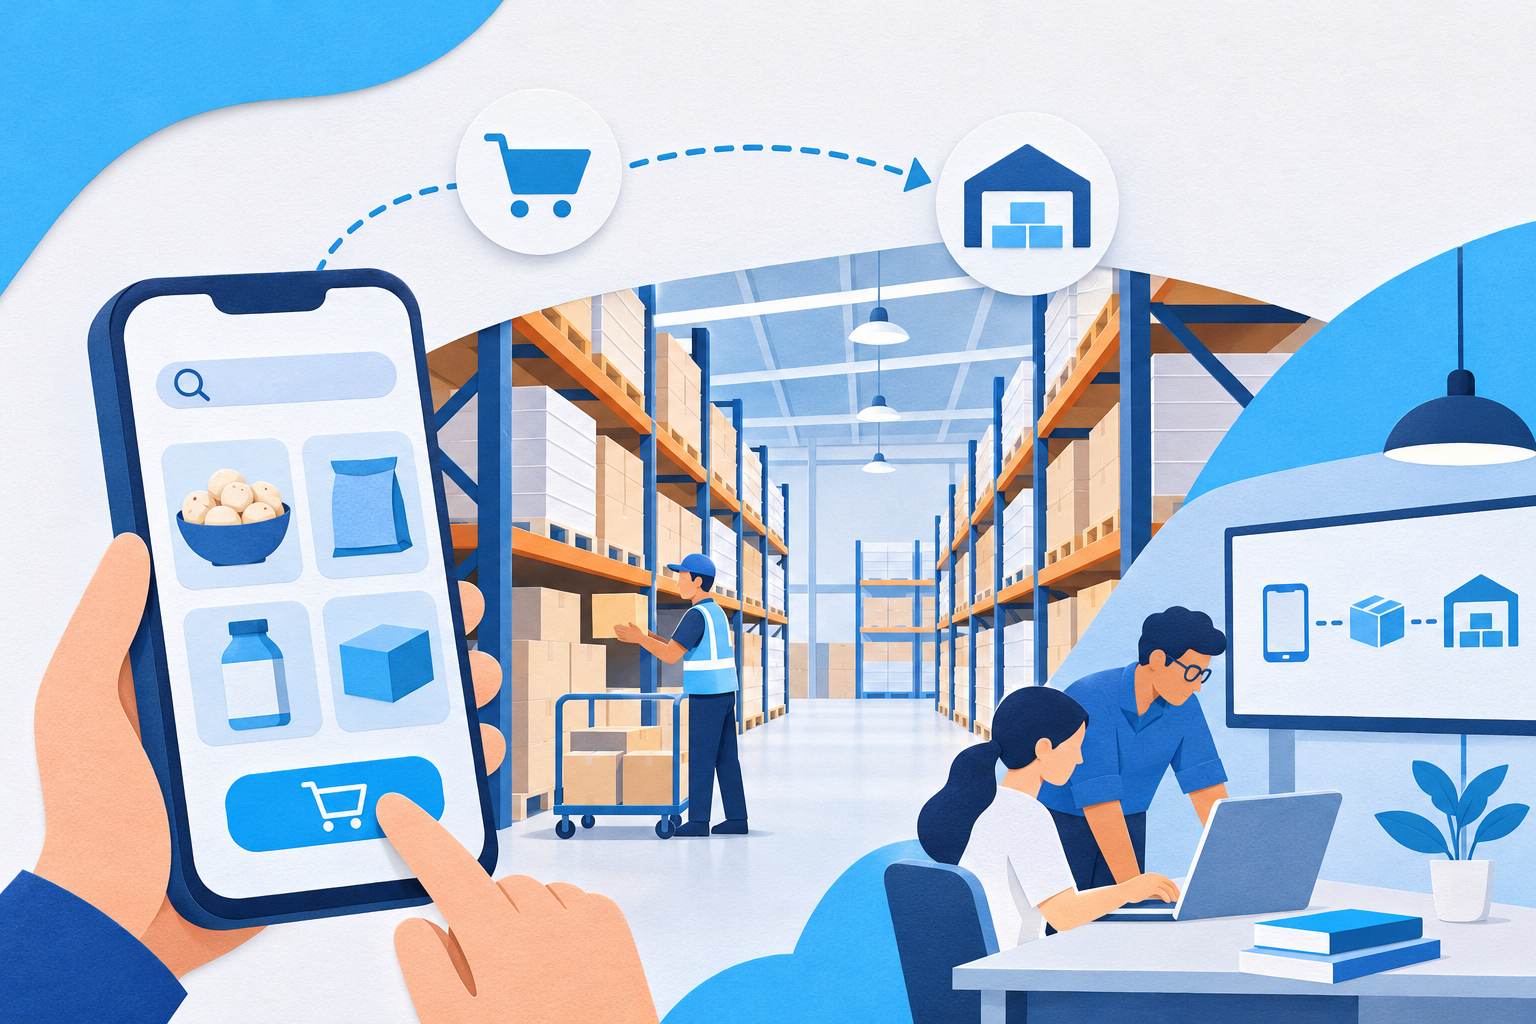
A vacant shop near customers and a large warehouse outside the city are not competing answers to the same quick-commerce problem. A delivery network can need both. The first shortens the journey to the doorstep; the second gives the neighbourhood stores somewhere to replenish from.
Cover: an original AI-generated conceptual illustration of two logistics property formats, not an actual facility.
That distinction matters when reading the sector's property forecasts. More demand for urban logistics does not mean every available commercial unit will suit a delivery platform.
The Breakdown
In its October 26, 2026 report, CBRE projects about 75 million square feet of cumulative urban logistics stock by 2030: approximately 42 million in dark stores and 33 million in larger replenishment hubs. These are forecast stock levels, not 75 million square feet of new leases signed today or an annual leasing target.
A different test for each building
For a neighbourhood unit, being close to customers is only the beginning. CBRE highlights ground-floor access, reliable power for cold storage, loading arrangements and space that separates replenishment from rider movements.
The practical implication is that a property's usable layout matters alongside its rent and address. A low-cost unit that needs extensive alterations, or makes incoming stock and outgoing riders compete for access, may be a poor operational fit.
For the larger hub, the question shifts towards the stores it can support. Its value is tied to a network rather than to walk-in shopping. More storage capacity is useful only if inventory can move through it to the right locations.
Growth is not the same as utilisation
Eternal's FY26 annual report illustrates the distinction. At March 31, 2026, Blinkit had 2,243 stores across more than 250 cities. Separately, it reported managing 8.5 million square feet of warehousing space after expanding its backend infrastructure. Those are company-reported figures for one operator at a specific date, not a sector total or a measurement of CBRE's projected 2030 demand.
A wider network also creates a sequencing problem. Space can be leased before nearby demand is mature enough to use it efficiently. Conversely, crowded stores may need more replenishment capacity before the operator opens many additional customer-facing locations. Store counts alone cannot resolve that distinction.
CBRE's historical leasing analysis covers Blinkit, Instamart and Zepto from 2021 through the first half of 2026. It is not a census of every quick-commerce operator, and its forecasts should not be mistaken for committed development plans.
The Crunch
For Indian property owners and operators, the useful question is not simply how much quick commerce will grow. It is which part of the network a building can serve, what it costs to make that building usable, and whether enough activity will follow.
Related category: Business & Brands.
Leave your thoughts