
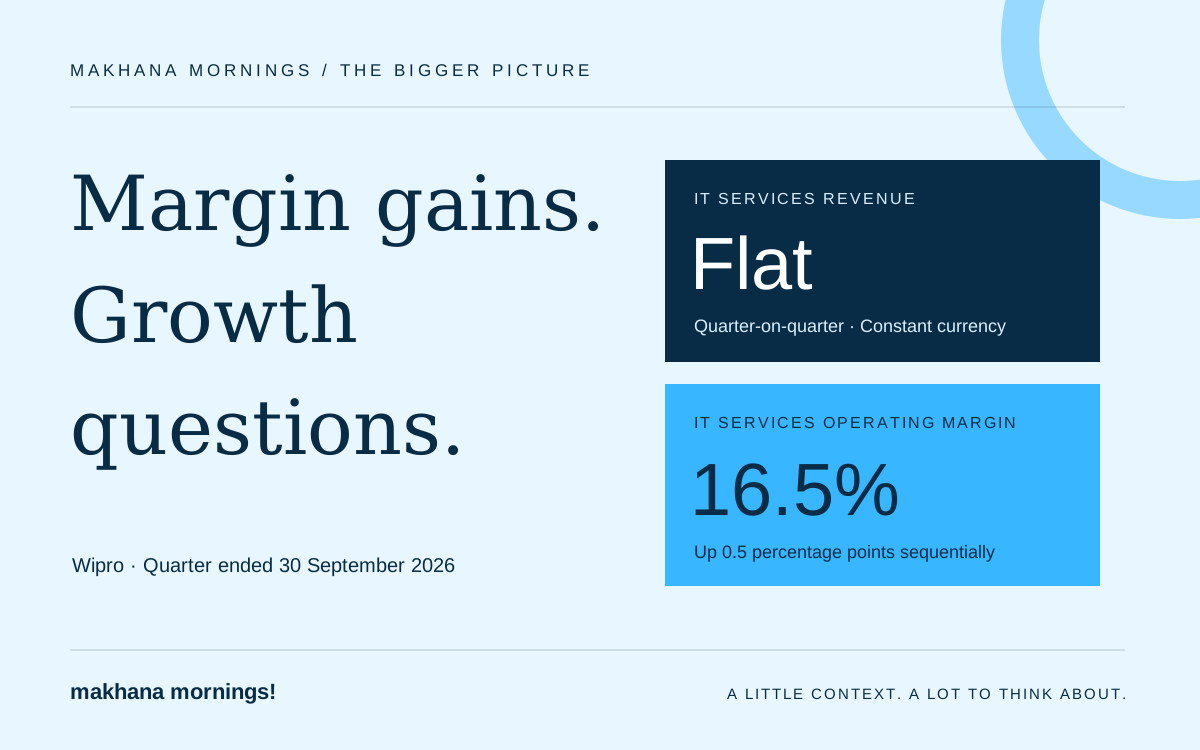
In its latest quarter, Wipro kept more of each rupee of sales as operating profit, giving it a higher operating margin. But revenue barely changed, and the value of large deals signed fell sharply.
The September results show why it helps to look at all three measures. A better margin is a gain, but the next question is whether stronger sales can follow.
The Breakdown
For the quarter ended September 30, 2026, IT-services revenue was $2.61 billion. That was down 0.1% from the June quarter in reported dollars, but flat once changes in exchange rates were removed. This is called constant-currency growth. On that basis, revenue rose 0.6% from a year earlier.
The IT-services operating margin rose to 16.5%, from 16% in the June quarter. The gain was 0.5 percentage points, or 50 basis points. Even so, the margin was still 20 basis points below its level a year earlier.
Total bookings, or the value of deals signed, came to $2.60 billion. That was down 22.9% from the June quarter after currency changes were removed. Large deals made up $674 million of that total, down 58.6% on the same basis.
The group’s rupee results showed stronger growth. Consolidated revenue, which covers the group, rose 9.1% from a year earlier to about ₹24,753 crore. That was slightly above the average forecast from analysts. But this figure covers a different scope and measure from IT-services revenue at constant currency. The two growth rates cannot be used in place of each other.
Why This Matters
Bookings include new work, renewed deals and increases to current deals. The revenue from that work comes in over the life of each contract. A drop in bookings need not cause the same drop in sales right away.
It still matters because deals signed today help build future work. Large deals can also make results swing from one quarter to the next, so one sharp fall is a reason to watch what follows. It does not prove that demand has changed for good.
For India’s tech workers and suppliers, the key questions are when projects will start, how fast they will grow and what work clients are buying. A higher margin alone cannot answer those questions or show a trend in hiring.
The Big Picture
For the December quarter, Wipro forecasts a change in IT-services revenue of between a 1.5% fall and 0.5% growth. That range is measured against the September quarter after currency changes are removed. It leaves room for both a further fall and a small rise.
Management says its spending on AI is opening up more chances to help clients change their businesses. Those chances still need to turn into signed work and then sales. An AI announcement, a signed deal and revenue booked in the accounts mark different stages.
The Crunch
Watch three things together: whether bookings recover, whether those deals turn into sales growth and whether the higher margin holds.
Wipro has improved the share of sales it keeps as operating profit. Its next test is to keep that gain while growing the work it delivers.