
Ampere has already exceeded its previous full-year electric two-wheeler registrations, according to Greaves Electric Mobility. The business question now extends beyond the volume milestone: can a larger sales and service network support that growing customer base while improving financial performance?
The Breakdown
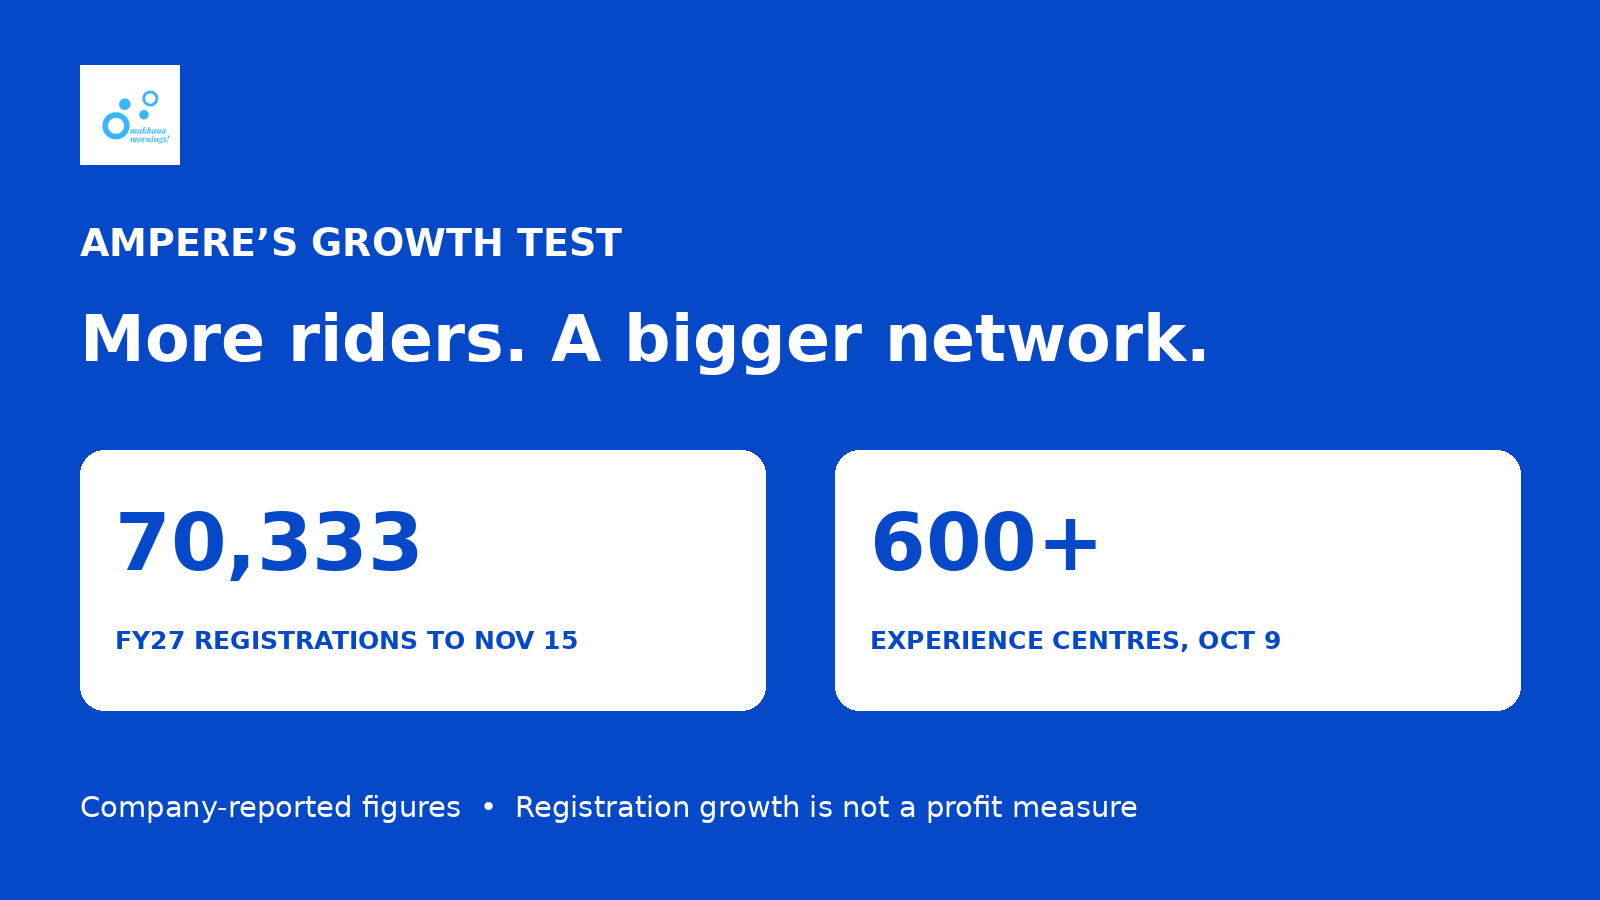
In its November 16 release, the company reported 70,333 VAHAN registrations in FY27 through November 15. That compares with 36,452 in the corresponding prior-year period, an increase of about 93%, and 61,842 for the whole of FY26.
These comparisons answer different questions. The same-period figure measures year-on-year growth; the full-year comparison marks a threshold already passed. Neither is a forecast for the rest of FY27.
The release also places Ampere fifth with 5.7% market share. Its headline bullet explicitly identifies that share as November 2026 through November 15, not the financial year to date. The figures are the company’s account of VAHAN registrations, not an independent Makhana Mornings extraction.
The network behind the milestone
There is a dated expansion story alongside those registrations. An October 9 company announcement reported more than 50 new experience centres across 15 states during Navratri. It put the network at more than 600 centres, compared with roughly 300 a little over a year earlier.
That is a larger physical footprint for demonstrations, sales and service. It does not establish that the expansion caused the subsequent registration increase, or that every location delivers the same ownership experience.
Growth and profitability are separate tests
Greaves Cotton’s October 29 results release gives earlier financial context. For the quarter ended September 30, Greaves Electric Mobility’s consolidated revenue was ₹410 crore, against ₹199 crore a year earlier. The company said EBITDA losses had halved year on year.
Losses narrowing is different from a business becoming profitable. Those quarterly financial figures also cover GEML, including its broader electric-mobility operations, rather than providing a standalone profit account for Ampere scooters. They should not be divided by the later registration total to estimate revenue or profit per scooter.
The Crunch
A growing installed base makes service capacity, spare-parts availability and the economics of individual outlets worth watching. The announcements establish expansion and registration momentum; they do not quantify those customer outcomes. The next useful evidence is sustained demand alongside better financial results and dependable support after the sale.
Leave your thoughts