
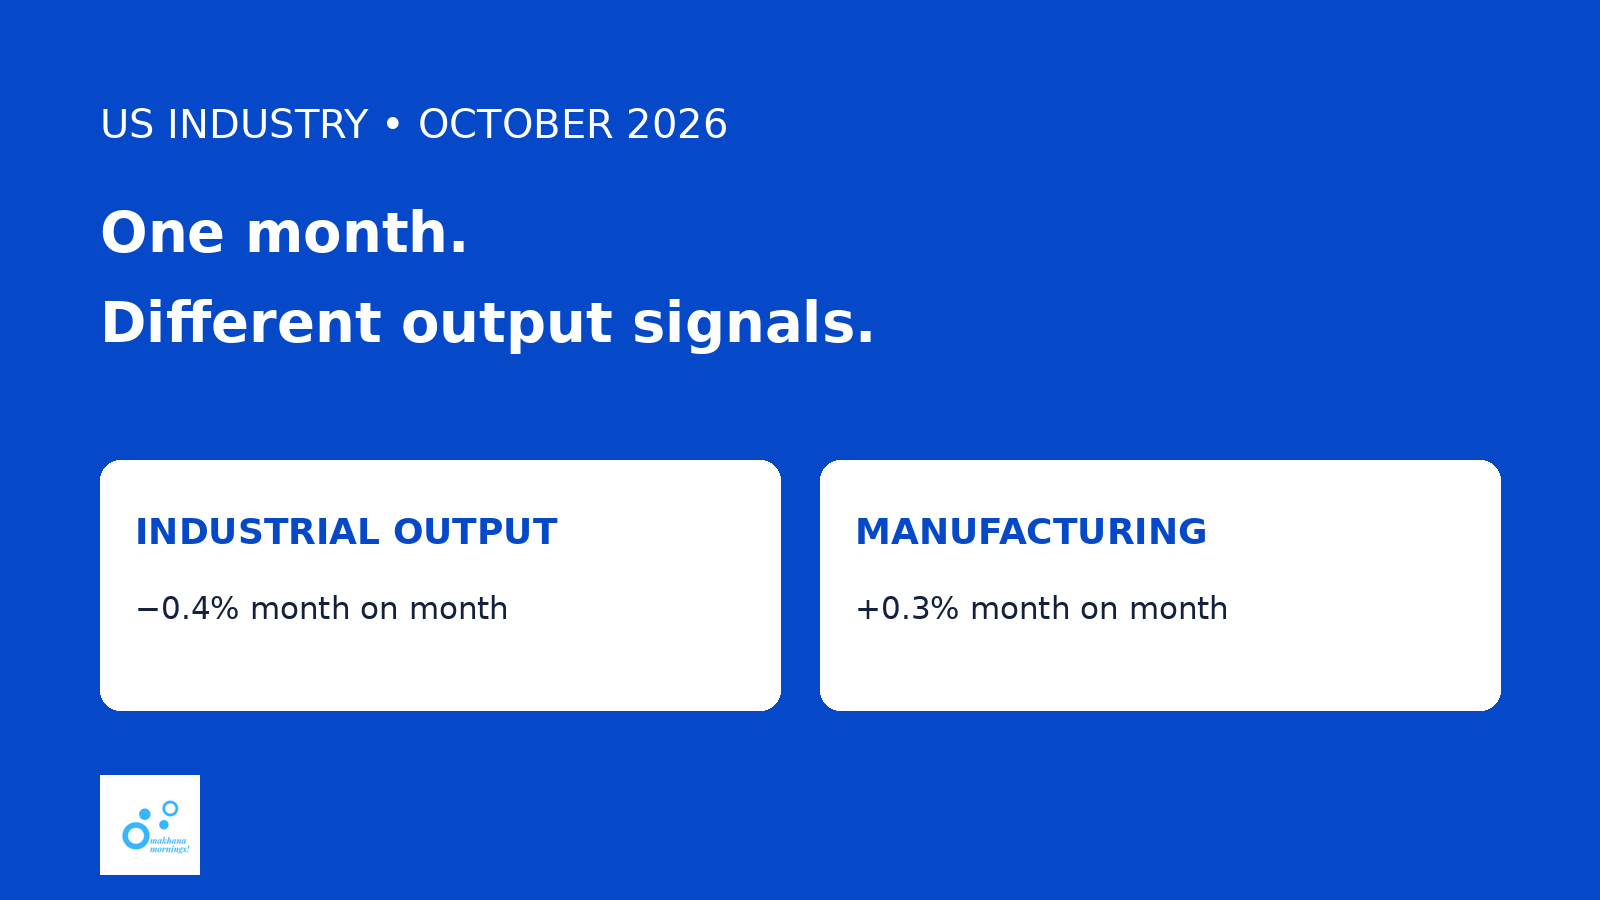
US industrial output fell in October, but factory output rose. Both statements can be true because the headline index includes more than manufacturing.
The Federal Reserve’s 17 November release puts the seasonally adjusted monthly decline in industrial production at 0.4%. Manufacturing rose 0.3%, while mining fell 0.8% and utilities dropped 4.3%. Total industrial output remained 2.1% above its year-earlier level.
The factory number also needs unpacking. Motor vehicles and parts output increased 4.4%; manufacturing excluding that group edged down 0.1%. A positive factory headline was therefore not evidence of a uniform improvement across producers.
October’s figures are preliminary. The Fed plans an annual revision on 24 November, incorporating updated benchmark data and revising seasonal factors and other inputs.
Read the components before the conclusion
For a business reading economic headlines, the first question is what the measure actually includes. A supplier selling machinery to factories, a mining-equipment company and a utility can face different conditions even when they appear inside the same broad index.
The second question is how widely the movement is shared. An aggregate can rise because a heavily weighted industry performs strongly while other parts remain flat or decline. It is not necessary to choose between “industry is weakening” and “factories are strengthening” without first specifying the group and comparison.
Monthly and annual comparisons also answer different questions. The former describes the latest movement; the latter compares output with its level a year earlier. Neither alone establishes a sustained trend, and one industrial release does not settle whether the wider economy is in recession.
For Indian exporters, this is a reason to look for evidence closer to their own customers: sector output, order books and delivery schedules. The US headline is useful context, not proof that orders for a particular Indian business have risen or fallen.
Leave your thoughts